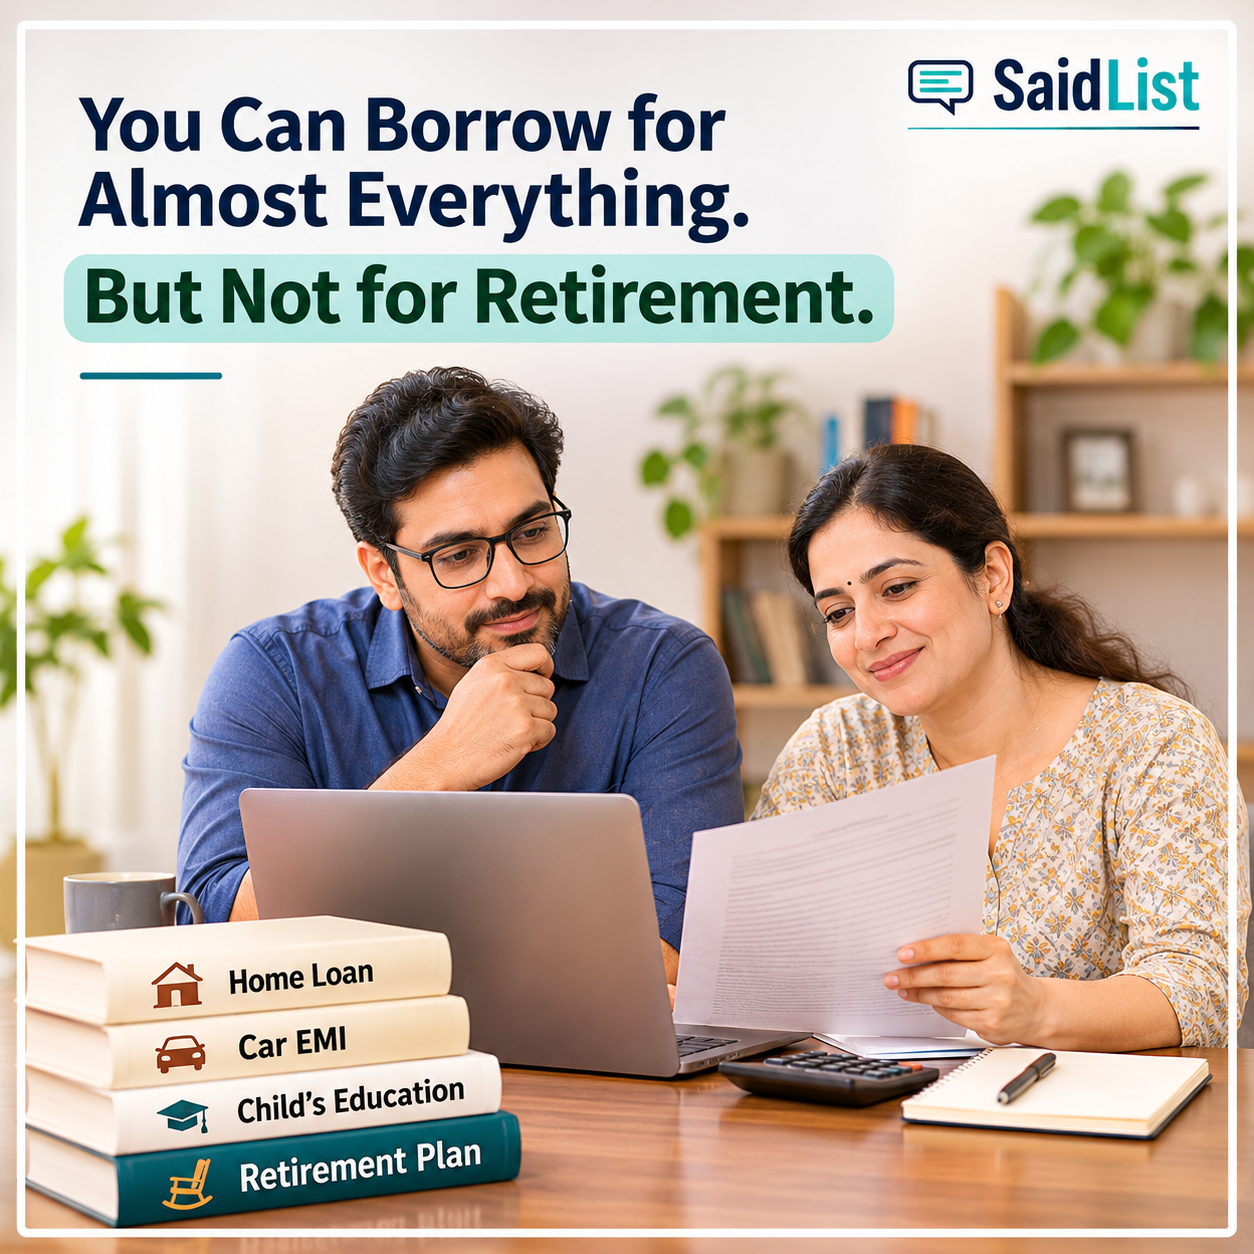
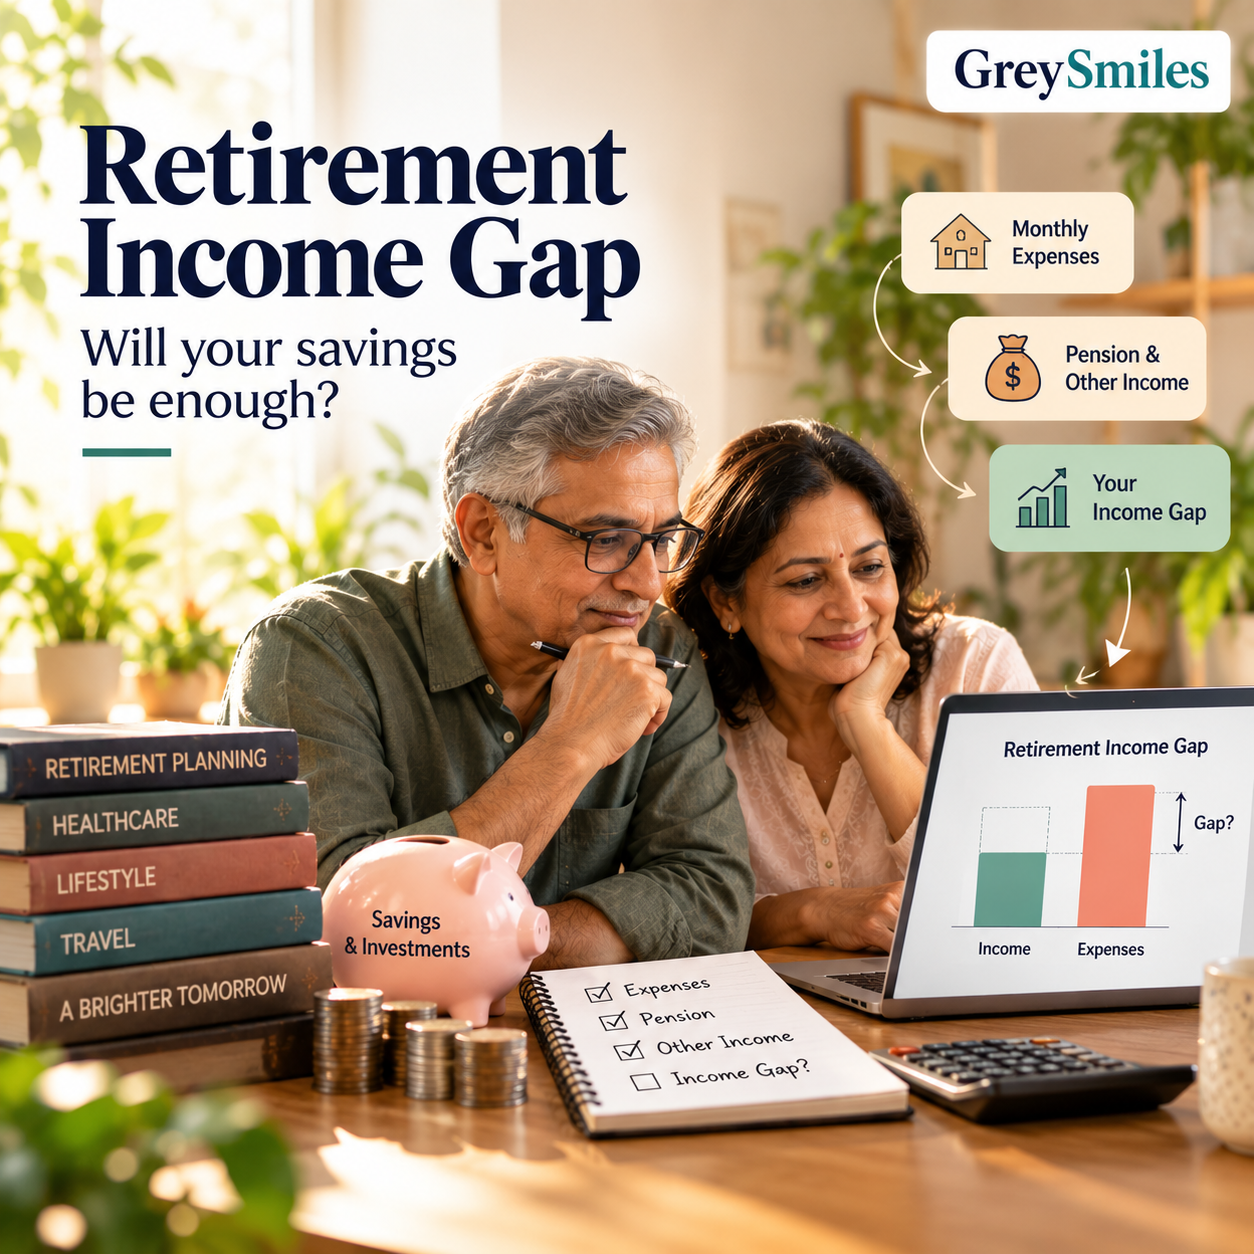
Retirement planning in your 30s and 40s is essential because home loans, car EMIs, children’s education and family responsibilities can leave little room for long-term savings. While these financial commitments may have fixed repayment schedules, retirement requires a corpus built gradually over several years.
For many Indian households, monthly income is already divided between loan repayments, household expenses and family needs. Retirement savings often receive whatever remains at the end of the month, making them easy to postpone.
The problem is that you cannot take another loan to replace your salary after retirement. You need savings and investments that can support your everyday expenses when regular employment income stops.
The question, therefore, is simple: Are your current financial commitments leaving enough room for your retirement?
The Problem With Always Putting Retirement Last
A home loan can help a family purchase a property without having to save its entire cost upfront. A car loan can make a vehicle affordable through monthly instalments. An education loan can help a child access opportunities that might otherwise be difficult to finance.
These are not necessarily poor financial decisions. Borrowing can be useful when the repayment is manageable and the loan supports a considered goal.
The difficulty begins when retirement savings become dependent on whatever money is left after all other expenses.
In your 30s, retirement may appear distant. By your 40s, school fees, home loan repayments, parents’ healthcare needs and career responsibilities may seem much more urgent. You may postpone retirement contributions year after year.
Over time, this creates a gap between the lifestyle you are funding today and the financial resources you are building for tomorrow.
How EMIs Can Quietly Reduce Your Retirement Savings
One EMI may seem manageable. But several instalments, combined with insurance premiums, household expenses, education costs and family responsibilities, can leave little room for long-term investments.
The issue is often the cumulative effect of financial commitments.
Consider a familiar situation. Your salary increases, household spending rises, you take on another loan, but your retirement contribution remains unchanged. Although your income has grown, the amount being invested for your future has not kept pace.
A useful starting point is to divide your monthly income into four broad categories:
- Essential expenses: Housing, food, utilities, healthcare and other necessities.
- Financial commitments: EMIs, insurance premiums and contractual payments.
- Flexible spending: Discretionary purchases and expenses that can be adjusted.
- Future-focused contributions: Retirement investments, emergency savings and other long-term goals.
This exercise is not about eliminating every pleasure from your present life. It is about ensuring that your future is not funded only if money happens to be left over.
Can You Simply Work Until 65 or 70?
Many people assume they can continue working well beyond the traditional retirement age. For some, this may be a welcome choice. They may enjoy their profession, remain healthy and want to stay professionally active.
But there is a difference between choosing to work longer and depending on it because retirement savings are inadequate.
Health conditions, caregiving responsibilities, redundancy, changes in an industry or a personal desire to slow down can affect your ability to continue working. Self-employment and consulting may also provide irregular income rather than a dependable salary.
Later-life work can be one possible source of income. It should not be the only assumption on which your retirement plan depends.
A more sensible approach is to estimate your retirement age and then consider what would happen if you had to stop working earlier or earn less than expected. A plan that can accommodate different circumstances offers greater flexibility.
Is Your House Enough to Fund Your Retirement?
For many Indian families, a house is their most valuable asset. It may provide security and could potentially support retirement finances through options such as downsizing, renting out a property or exploring a suitable loan against property.
However, owning a valuable property is not the same as having regular retirement income.
Property may be difficult to convert into cash without selling it, relocating, taking on repayment obligations or accepting other financial risks. Borrowing against an asset can also introduce costs and obligations at a stage when dependable income may be limited.
Your home can be an important part of your retirement plan, but its value should not automatically be treated as money available for everyday expenses.
Start With an Estimate, Not a Perfect Number
Retirement planning becomes easier when you move from a general concern about the future to an estimate that you can review.
Start by considering:
- The lifestyle you expect after retirement.
- The age at which you would like to stop working.
- Your existing savings and investments.
- The income you may receive after retirement.
- Inflation and the likely increase in healthcare expenses.
- How long your retirement savings may need to last.
These are estimates, not guarantees. Investment returns, inflation and personal circumstances can change. It is therefore useful to test different assumptions rather than rely on a single projection.
A retirement corpus estimate can help you understand whether your current savings rate, expected retirement age and future lifestyle are broadly aligned.
Five Questions Worth Asking Yourself
If you are in your 30s or 40s, take a moment to consider:
- How much do I currently contribute towards retirement savings every month?
- Have these contributions increased as my income has grown?
- How much of my take-home income is committed to EMIs and other fixed payments?
- What would happen if I had to stop working earlier than planned?
- When did I last estimate my retirement needs using updated expenses and assumptions?
Your answers may point towards a practical next step. You might increase your retirement contribution gradually, review expensive debt, redirect part of a loan repayment towards investments once the loan ends, or reconsider your expected retirement age and lifestyle.
You do not necessarily have to choose between repaying a home loan and saving for retirement. The right balance depends on factors such as the interest rate, remaining loan term, emergency savings, income stability and existing investments.
The important thing is to avoid treating retirement savings as something that must wait until every other financial commitment has ended.
You Do Not Have to Choose Between Today and Tomorrow
A sensible retirement plan does not require you to stop spending, avoid every loan or invest every spare rupee.
You may need a home. Your children’s education may be a priority. Your parents may need financial support. You may also want to travel, enjoy life and make room for experiences while you are healthy and active.
These goals can coexist, but they need to be considered together.
A loan can help you pay for something you need or value today. Retirement savings help protect your ability to make choices when a regular salary is no longer available.
You do not need to solve your entire retirement plan this month. But you do need to stop treating it as the one financial goal that can always wait.
Give your future a place in today’s budget, before every other commitment takes that place away.
This article is based on the retirement-planning perspective explored by GreySmiles, an India-focused platform covering retirement, ageing and independent living. Read the original article and explore its retirement-planning resources at GreySmiles.
Disclaimer: This article is for general educational purposes only and should not be treated as personalised financial, investment, tax or legal advice. Retirement estimates depend on individual circumstances and the assumptions used.